A Mortgage-Rate Spike. Buyers Backed Off. Sellers Didn’t Blink.
Kansas City housing · October 2026
In Kansas City, rates hit 7.4 percent just as October offers were being written, and new contracts fell by a fifth. But the region kept adding jobs and residents, sellers didn’t rush to list, and the median price stayed at $330,000. The strain landed on particular people and places.
Buyers signed 2,506 contracts in October, 19.8 percent fewer than a year earlier, after the 30-year mortgage rate peaked at 7.40 percent, its highest since November 2023. The median sale price held at $330,000, and the region had 2.9 months of supply. The metro still added jobs and residents; the strain showed up in monthly payments and in particular ZIP codes.
19.8% fewer$330,000 median7.40% rate2.9 months
19.8%fewer contracts than last October
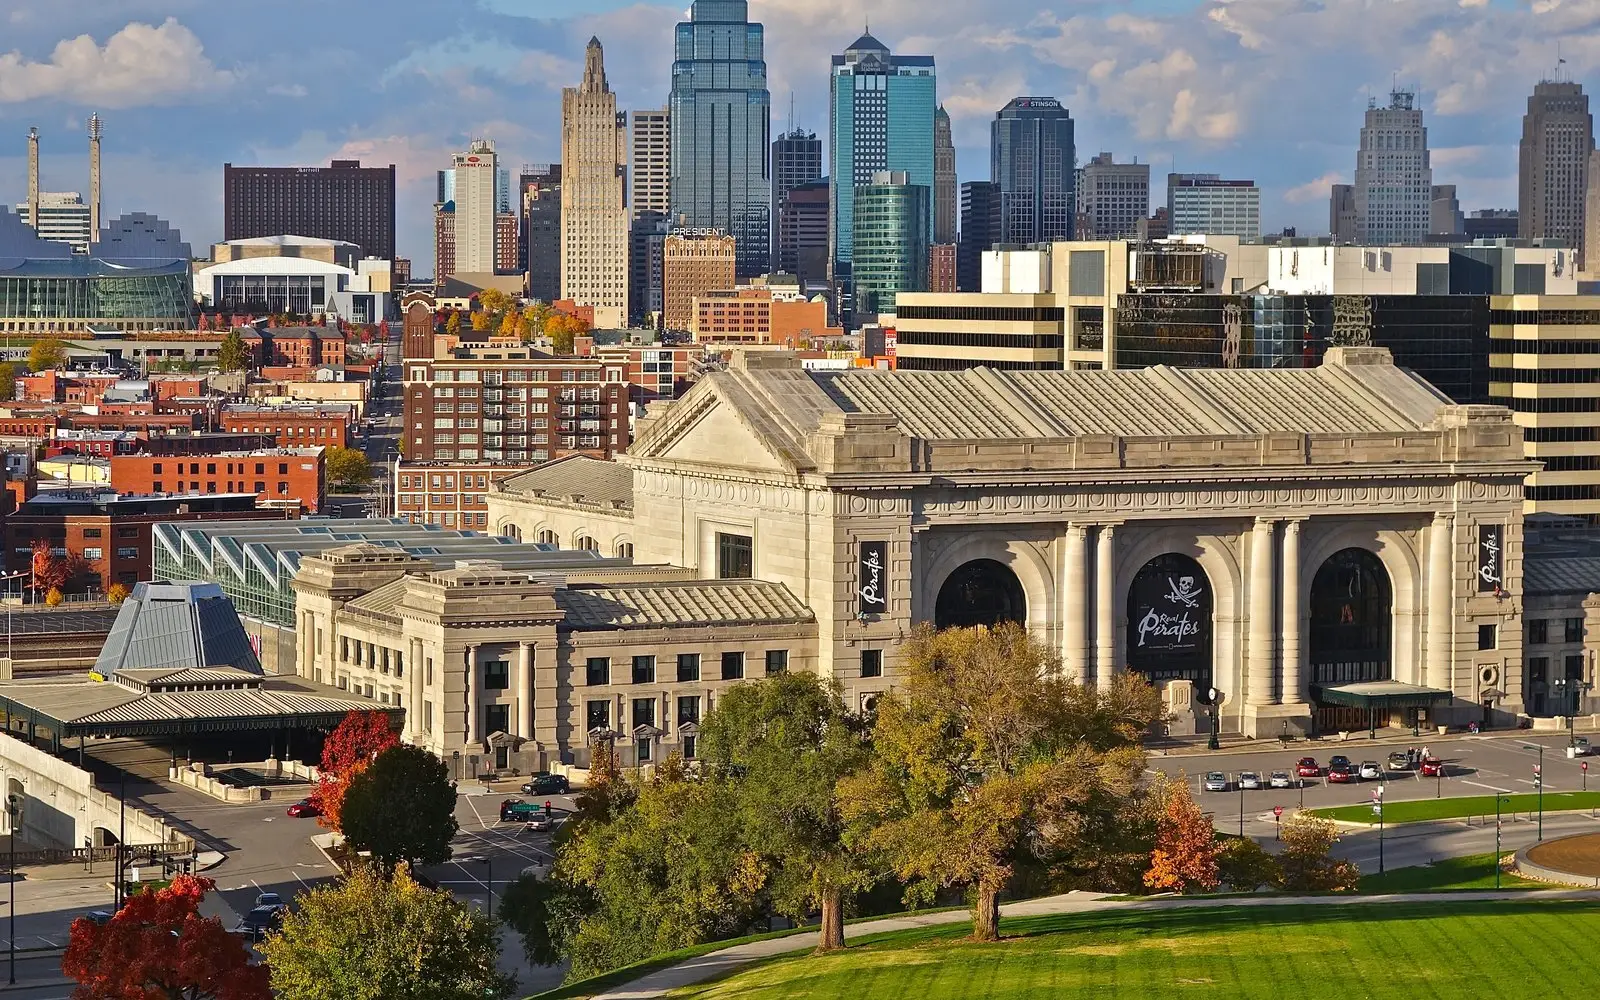
Photo: Dean Hochman, Kansas city, CC BY 2.0, via Wikimedia Commons. Cropped by Saving KC Homebuyers.
Last October, buyers signed 3,123 contracts. This October, 617 fewer.
3,123October 2025
2,506October 2026
−617−19.8 percent
October 20253,123
October 20262,506 -617 (-19.8%)
October 2025: 3,123 contracts, shown as a charcoal bar. October 2026: 2,506 contracts on the same scale, shown as a shorter charcoal bar. The missing 617 contracts, 19.8 percent, are the hatched red segment labeled -617 (-19.8%).
Takeaway. Last October, buyers signed 3,123 contracts. This October they signed 2,506, which is 617 fewer, or 19.8 percent.
Pending sales, all residential, Heartland MLS (19 counties). Source: Kansas City Regional Association of Realtors, Local Market Update, October 2026, current as of Nov. 7, 2026.
Key takeaways
Buyers signed 2,506 contracts in October, 19.8 percent fewer than a year earlier. The 30-year mortgage rate peaked at 7.40 percent mid-month, its highest since November 2023.
The median sale price held at $330,000. With 2.9 months of supply, the region has far fewer homes for sale than the nation, at 4.8 months.
The monthly payment on a typical home rose most in Jackson and Wyandotte Counties, by 15 to 16 percent, because prices and rates went up together there.
The metro is still growing. It added 17,395 residents in the year to July 2025, and payrolls were up 6,000 jobs in September from a year earlier.
Lending
How fast did mortgage rates climb this fall?
The 30-year rate rose from 6.66 percent in late August to 7.40 percent in early October, the largest six-week climb since fall 2022. It has eased to 7.18 percent.2
Rates climbed their fastest in four years, right as fall buyers went shopping
Most housing slowdowns build over seasons. This one arrived in a few weeks, and you can see it in one line.
The 30-year mortgage rate, week by week
Freddie Mac Primary Mortgage Market Survey, 30-year fixed average. Payment is principal and interest on $247,500, 75 percent of the $330,000 metro median. Drag across the chart to read any week.
Takeaway. From late August to early October the 30-year rate rose from 6.66 percent to 7.40 percent, the largest six-week climb since the fall of 2022, and it peaked just as fall buyers were writing offers.
For most of 2026, the rate on a 30-year mortgage barely moved. Freddie Mac’s weekly average touched its low for the year, 5.98 percent, on Feb. 26, and spent the summer between about 6.4 and 6.7 percent.
Then it took off. From late August to early October, the average rose from 6.66 percent to 7.40 percent. It had not climbed that much in six weeks since the fall of 2022.
The peak, 7.40 percent, came in the weeks of Oct. 8 and Oct. 15, right when fall buyers were writing offers. October’s readings averaged 7.33 percent, up from 6.25 a year earlier. Buyers signed 19.8 percent fewer contracts.
Rates have eased since, to 7.18 percent on Nov. 5. On a loan for 75 percent of the median home, that is $37 a month below the peak and still $158 a month above a year ago.
For a buyer who started looking in February, the change was hard to miss. The monthly principal and interest on a $247,500 loan was $1,481 at the February low. At the October peak it was $1,714, or $233 more for the same house.
Closings lag contracts by a month or more, so the full effect has not reached the sales totals yet. Closed sales still fell 10.6 percent in October, to 2,953.
Buyers
Where did monthly payments rise the most?
Monthly payments rose most in Jackson and Wyandotte Counties, by 15 to 16 percent. The typical Jackson County home costs $207 more a month.12
The same house costs more each month, most of all where houses are cheapest
Prices alone would have handed some buyers a break. Medians fell in Johnson, Platte and Clay Counties. The higher rate erased those discounts everywhere.
Take the typical Johnson County home. Its median price fell 2.7 percent, to $452,500, which cuts about $58 from the monthly payment. The higher rate adds $216. The buyer still pays $158 more than a year ago.
Jackson County buyers were hit twice. The median rose 5.5 percent, to $290,000, and the rate rose too. The payment on the typical home there is up $207 a month, or 16 percent. In Wyandotte County it is up 15 percent. Those are the two core counties with the lowest prices, where buyers have the least room to absorb it.
What a year did to the monthly payment on the typical home
Principal and interest, 25 percent down. A year ago: last October’s median price at 6.22 percent. Now: this October’s median at 7.18 percent.
Change from the priceChange from the rateA year ago
Takeaway. The higher rate erased price cuts everywhere. Payments rose most in Jackson and Wyandotte Counties, by 15 to 16 percent, because prices and rates went up together there.
Sources: KCRAR Local Market Updates, October 2026; Freddie Mac PMMS (6.22 percent, week of Nov. 6, 2025; 7.18 percent, week of Nov. 5, 2026). Taxes and insurance excluded.See the numbers
At the bottom of the market, a loan competes with cash
Buyers who need a mortgage face another problem in the cheapest homes: competition from buyers who don’t.
Guess first. Of the homes that sold for under $150,000 in October, what share were bought with cash?
Cash share of October sales, by price
Each square is 1 percent of the sales in that price range, rounded. Red squares were paid in cash.
Takeaway. Across the five core counties, 19.9 percent of October sales were cash. Below $150,000, it was 56.2 percent. All 10 homes that sold for under $50,000 went to a cash buyer.
Source: Heartland MLS (Matrix) listing extract of October 2026 closings in Jackson, Clay, Platte, Johnson and Wyandotte Counties, pulled Nov. 2, 2026: 1,910 sales with recorded sale terms. The MLS does not capture most off-market sales.See the numbers
Across all five core counties, 19.9 percent of October sales were cash. Below $150,000, it was 56.2 percent. Every one of the 10 homes that sold for under $50,000 went to a cash buyer. The share falls to 12.7 percent between $350,000 and $400,000, then climbs again above $400,000, where buyers with equity from a previous home often skip the loan.
Sellers
Did unsold homes pile up when buyers backed off?
Active listings rose 1.5 percent, to 9,139. That is 2.9 months of supply. Homes still sold for 96.4 percent of the original asking price.16
Sellers didn’t flinch, except in Jackson County
When buyers pull back, you might expect unsold homes to pile up. That hasn’t happened. Active listings rose just 1.5 percent from a year earlier, to 9,139. At October’s pace of sales, that is 2.9 months of supply, the same as last year.
Sellers are mostly still getting their price. Across Heartland MLS, homes sold for 96.4 percent of their original asking price, down from 96.9. In Johnson County, sellers got 99.1 percent, and homes sold two days faster than a year ago.
Jackson County is the exception. It is the only core county where homes took longer to sell, 46 days instead of 38, and the only one with more than three months of supply.
Jackson is the only core county where selling got slower
October 2025October 2026Jackson County, October 2026
Takeaway. Jackson County is the only core county where homes took longer to sell, 46 days instead of 38, and the only one with more than three months of supply.
Source: KCRAR Local Market Updates, October 2026, current as of Nov. 7, 2026. Each county compares October 2026 as first reported with October 2025 as revised. U.S. supply is the National Association of Realtors’ September 2026 figure.See the numbers
Failed listings
How many Kansas City listings failed to sell?
In September, 28.9 percent of Jackson County listings that left the market did not sell. In Wyandotte County it was 33.5 percent.1
Some sellers are giving up. In September, before the October slowdown, 28.9 percent of the Jackson County listings that left the market did so without a sale. In Wyandotte County it was 33.5 percent. In October, 151 listings expired and 81 were withdrawn across the five counties.
Share of listings that left the market without selling, September 2026
Toggle gross or net fail rates. Net is the stricter measure. Hover a bar for the county figure.
Takeaway. In September, 33.5 percent of Wyandotte County listings and 28.9 percent of Jackson County listings that left the market did so without a sale, the two highest gross fail rates among the five core counties. The net rates were 30.3 and 23.8 percent.
Expired, withdrawn or canceled listings as a share of all listings that left the market. Gross and net rates are the KCRAR county figures for September 2026, the latest complete month for this measure. Source: KCRAR / county Local Market Updates, September 2026.
October expired and withdrawn listings, in a narrower ZIP-code slice
A Heartland MLS Matrix extract of October 2026 expired and withdrawn listings, limited to ZIP codes with at least 20 October sales and a median close price from $200,000 to $400,000. 55 listings (29 expired, 26 withdrawn) across 20 ZIP codes. This is not the full 232-count Matrix slice (151 expired, 81 withdrawn) and not a full fail rate. Hover a bar for counts. Median last list price and median days on market are shown only when a county has at least five listings in the slice. Counties with fewer than 10 listings are flagged as a small sample. No MLS numbers, addresses or single-listing details are shown.
Takeaway. In this 55-listing slice, Jackson County accounted for 28 of the 55 expired or withdrawn listings. Across the slice, the median last list price was $320,000 and the median days on market was 78. Expired listings in the slice had a median last list price of $360,000 and a median 101 days on market; withdrawn listings had a median last list price of $303,250 and a median 54.5 days.
Source: Saving KC aggregate of a Heartland MLS Matrix extract, pulled Nov. 9, 2026, for October 1-31, 2026 off-market dates in the ZIP filter described above. Area totals only. Heartland MLS Rule 13: no listing-level records are published. Counties with fewer than five listings in the slice have counts only, not medians.See the county totals
County
Expired
Withdrawn
Total
Median last list price
Median days on market
Jackson
19
9
28
$303,250
85.5
Johnson
5
6
11
$365,000
78
Clay
3
7
10
$340,000
58.5
Wyandotte
1
3
4
n/a (n under 5)
n/a (n under 5)
Platte
1
1
2
n/a (n under 5)
n/a (n under 5)
Slice total
29
26
55
$320,000
78
ZIP codes in this slice with at least five listings, all small samples (n under 10): 64133 in Jackson County, 6 listings, median last list price $332,000, median 121.5 days on market; 64138 in Jackson County, 5 listings, $214,500 and 123 days; 66212 in Johnson County, 5 listings, $365,000 and 92 days. Other ZIP codes in the slice had fewer than five listings, so their medians are not shown.
If your listing expired or you withdrew it, that is one outcome in a market where buyers signed 19.8 percent fewer contracts than a year earlier. This page is a market report, not a price quote and not a cash offer. A local Kansas City team can walk through your options in plain English, with no pressure and no obligation.
Two-minute self-check7 questions · no typing
Sell it or list it? Guess wrong and it costs you.
Tap the picture that fits. No wrong answers.
0 of 7 answered
Question 1of 7
Does the house need work?
Question 2of 7
Do you need to sell by a certain date?
Question 3of 7
Would it be hard to let buyers walk through the house?
Question 4of 7
Is there a legal or money problem tied to the house?
Question 5of 7
Can you keep paying the bills on the house for three more months?
Question 6of 7
Do you want the highest price more than a fast, sure sale?
Question 7of 7
Could a buyer get a home loan for the house as it is?
7 to unlock
Answer the questions to see your result.
Neighborhoods
How does the Kansas City market split by ZIP code?
All 26 Johnson County ZIP codes with at least five sales had a median of $300,000 or more. Jackson County medians ran from $60,000 to more than $700,000.
On the map, the region splits by price, by speed and by cash
County totals smooth over a lot. Here are the 129 ZIP codes in the five core counties that the Census Bureau maps, using the agent-only MLS data that county reports are built from.
Median sale price by ZIP code, October 2026
Each circle is a ZIP code, sized by its October sales and shaded by median sale price. The most expensive homes run south through Johnson County on the Kansas side. The least expensive cluster on Kansas City’s East Side and in Kansas City, Kan.
Line the ZIP codes up by county and the split is stark. All 26 Johnson County ZIP codes with at least five sales had a median of $300,000 or more. In Jackson County, 14 of 38 were under $250,000, and the medians ranged from $60,000 to more than $700,000.
Speed follows the same line. In the typical Johnson County ZIP code, homes went under contract in about eight days. In the typical Jackson County ZIP code, it took about 25. The slowest ZIP code with at least 10 sales was 64128, on the East Side, at 58 days.
Cash shows up in two very different places. One is the East Side, where homes are cheapest: in 64127, two-thirds of buyers paid cash. The other runs along both sides of State Line Road, around the Country Club Plaza, Brookside and Prairie Village, where about half of buyers paid cash. Both ends of the price range, in one picture.
Takeaway. Price, days to contract and cash share all vary widely by ZIP code. Johnson County medians sit at $300,000 or more where there were at least five sales; Jackson County medians run from $60,000 to more than $700,000.
Map: Heartland MLS (Matrix) ZIP rollup of October 2026 closings pulled Nov. 9, 2026, and listing extract pulled Nov. 2 (cash share). ZIP codes with fewer than five sales are shown as hollow rings; one sale can set their median. Days to contract is the MLS’s days on market before a contract, which differs from the county reports’ measure. ZIP centers: Census Bureau 2020 Gazetteer. Three ZIP codes with no October sales have no mapped center and are left off.
Speed
Where are homes selling fastest and slowest, and why?
Among ZIP codes with 10 or more October sales, 66207 in Johnson County was fastest at 2 days to contract, and 64128 in Jackson County was slowest at 58 days. The typical Johnson County ZIP code was about eight days, and the typical Jackson County ZIP code about 25.
Five fastest
166207Johnson County2 days$505,750 median · 31.2% cash
266213Johnson County3 days$492,500 median · 17.4% cash
366112Wyandotte County3 days$213,500 median · 30.8% cash
466062Johnson County4 days$445,000 median · 12.1% cash
564114Jackson County4 days$345,000 median · 20.0% cash
Five slowest
164128Jackson County, East Side58 days$115,228 median · 30.0% cash
264075Jackson County51 days$359,000 median · 30.0% cash
364134Jackson County44 days$147,150 median · 34.4% cash
464137Jackson County43 days$230,000 median · 27.3% cash
566224Johnson County42 days$1,065,000 median · 26.7% cash
Bars share one scale, from 2 days to 58 days. When two ZIP codes had the same median days, the one with more October sales is listed first. Six ZIP codes tied at 4 days. 66062 (91 sales) and 64114 (35 sales) had the most, so they take the last two spots in the fast five.
The ranking uses the same October 2026 ZIP rollup as the map: median days to contract, median close price, sale count and cash share, and only ZIP codes with 10 or more sales. There are 70 of them. It matches the line on the map. In the typical Johnson County ZIP code, homes went under contract in about eight days. In the typical Jackson County ZIP code, it took about 25. The slowest ZIP code with at least 10 sales was 64128, on the East Side, at 58 days. The two middle Jackson County ZIP codes in this set took 24 and 25 days, which is that “about 25.” Both middle Johnson County ZIP codes took 8 days.
The fast group and the slow group differ on price, cash share and county. The middle price in the fast five is $445,000, against $230,000 in the slow five. The middle cash share is 20.0 percent, against 30.0 percent. Three of the five fastest are in Johnson County. Four of the five slowest are in Jackson County. Across all 70, 19 of the faster 35 ZIP codes are in Johnson County and 21 of the slower 35 are in Jackson County. Those are correlations, not causes. A lower price and a higher cash share travel with the slow end of this list, and they do not explain every ZIP code. 66112 in Wyandotte County is third-fastest at 3 days, with a $213,500 median and a 30.8 percent cash share. 66224 in Johnson County is fifth-slowest at 42 days, with a $1,065,000 median. 64114 in Jackson County is in the fast five, at 4 days.
The same month, the 30-year mortgage rate peaked at 7.40 percent. Monthly payments rose most in Jackson and Wyandotte Counties, by 15 to 16 percent. The payment on the typical Jackson County home is up $207 a month, or 16 percent. Four of the five slowest ZIP codes are in that county, so the slow end of the list lines up with where the payment rose. The figures line up. They do not show that the rate jump caused the extra days.
Listings that never sold sat longer, on a different clock. Homes that did sell in 64133 took a median 23 days, and in 64138 a median 26 days, so neither is in the five slowest. In the expired and withdrawn slice above, 64133 had 6 listings with a median 121.5 days on market, and 64138 had 5 listings with a median 123 days. Both samples are under 10. Those days describe listings that left the market without a sale, not days to contract on homes that sold.
Takeaway. With 10 or more sales, the fastest ZIP code was 66207 at 2 days and the slowest was 64128 at 58 days. The typical Johnson County ZIP code was about eight days, and the typical Jackson County ZIP code about 25. The fast five sit at a higher middle price and a lower cash share than the slow five, and they cluster in Johnson County while the slow five cluster in Jackson County. That is a correlation.
Median days to contract, median close price, cash share and sale counts: Heartland MLS (Matrix) ZIP rollup of October 2026 closings pulled Nov. 9, 2026, the same file as the map and the ZIP lookup. ZIP codes with fewer than 10 sales are left off. Days to contract is the MLS’s days on market before a contract. The 121.5 and 123 day figures are the expired and withdrawn slice above, not this ranking.
Your ZIP code
Look up a ZIP code
Investors
Can a financed rental still cover the mortgage?
The typical ZIP produced a 3.84 percent cap rate. Five of 71 cleared the 7.62 percent bar a loan needs, all in Jackson County under $170,000.23
For investors who borrow, the math works only at the very bottom
The MLS can’t tell an investor’s cash from a family’s. What the numbers can show is how hard a financed rental has become. At 7.18 percent with 25 percent down, a rental needs a capitalization rate of about 7.62 percent to cover its mortgage with a 25 percent cushion. The typical ZIP code with enough sales to measure produced 3.84 percent. Five of 71 cleared the bar. All five are in Jackson County, with median prices under $170,000.
Only five ZIP codes clear the cap rate a loan requires
Cap rate at each ZIP code’s median October price, 71 ZIP codes with at least 10 sales
Takeaway. Five of 71 ZIP codes with enough sales to measure cleared the 7.62 percent cap rate a loan requires. All five are in Jackson County, with median prices under $170,000. The typical ZIP produced 3.84 percent.
Assumes 25 percent down, a 30-year loan at 7.18 percent, 10 percent management, 5 percent for repairs, ACS rental vacancy and tax rates, and NAIC state average insurance. Rents: RentEdge, August 2026, with HUD FY2027 Small Area Fair Market Rents for 23 ZIP codes without a RentEdge figure.
Rents aren’t closing the gap. HUD’s fair market rents for 2027 jumped a median 14.1 percent for a three-bedroom home across these ZIP codes, to $2,045. But the market averages agents see in RentEdge sit below HUD’s benchmark in most of them, by a median of 6.2 percent. Insurance keeps rising, too: the federal producer price index for homeowners insurance is up 31.8 percent since January 2020.
Cash buyers
Why are cash buyers paying cash, and what do they earn?
In most ZIP codes, negative leverage makes cash the better choice, because the cap rate is below the 7.62 percent a loan needs. In the cheapest ZIP codes the math would favor a loan, but those houses often cannot get conventional financing, and cash closes faster.23
Negative leverage, in plain English: when the cap rate is below what the loan costs, borrowing lowers the return. The typical ZIP in this set produced a 3.84 percent cap rate. A 30-year loan at 7.18 percent, with 25 percent down, needs about a 7.62 percent cap rate before the payment is covered and a 25 percent cushion is left. Most of the 71 ZIP codes fall short of that, so cash is the better yield there.
For an all-cash rental, cash-on-cash before income taxes equals the cap rate. The buyer puts the whole price in, and the yearly net operating income is the yield. The five ZIP codes that clear 7.62 percent are also the five cheapest in the set. All five are in Jackson County. Set against the typical 3.84 percent, these are the cash yields at the bottom of the market:
ZIP
Median price
Cap rate
64130
$103,000
12.72%
64128
$115,228
12.36%
64132
$108,000
11.05%
64134
$147,150
8.03%
64052
$167,000
8.00%
Cap rate is the all-cash cash-on-cash yield before income taxes. Same expense model as the chart above: 10 percent management, 5 percent repairs, vacancy, taxes and insurance.
Try a ZIP from this report
3.84%Cap rate
3.84%All-cash cash-on-cash
−9.03%Financed cash-on-cashOnly if a lender will finance the house.
Defaults are ZIP 64014: median price $320,000 and rent $1,815, the ZIP at the 3.84 percent cap rate. Management stays at 10 percent of rent. Repairs start at 5 percent of rent. Vacancy, taxes and insurance stay at the dollars implied by that ZIP’s published cap rate, so the starting cap rate matches the chart. The financed column uses 25 percent down and a 30-year loan at 7.18 percent. Cash-on-cash is before income taxes.
In those cheapest ZIP codes, the math would favor a loan. They are also the houses that often cannot get conventional financing because of their condition. Cash closes faster. That is why 56.2 percent of sales below $150,000 were cash, and every sale below $50,000 was cash.
Takeaway. In most ZIP codes, negative leverage makes cash the better choice. In the cheapest ZIP codes a loan would earn more on paper, but those houses often cannot get conventional financing, and cash closes faster. That is why 56.2 percent of sales below $150,000 were cash, and every sale below $50,000 was cash.
Jobs and people
Is the Kansas City region still growing?
Payrolls were up 6,000 jobs from a year earlier, and unemployment was 3.4 percent. The metro added 17,395 residents in the year to July 2025.45
Underneath, the region is still growing
Why didn’t prices crack? The forces that drive housing demand over years, rather than weeks, are steady.
The Kansas City metro had 1,175,300 payroll jobs in September, 6,000 more than a year earlier. That is slow growth, 0.5 percent, but it is growth. Construction, which the government counts with mining and logging, added 3,300 jobs. Financial activities, the sector that includes mortgage lending and real estate, lost 2,000. The unemployment rate was 3.4 percent, about where it stood a year ago.
One caution: the labor force shrank by about 13,600 people over the year, so the low rate partly reflects fewer people looking for work.
Unemployment rate, Kansas City metro
Not seasonally adjusted, so compare the same month across years
Jobs gained or lost by industry, September 2026 vs. a year earlier
Payroll jobs, Kansas City MO-KS metro
Takeaway. The Kansas City metro had 1,175,300 payroll jobs in September, 6,000 more than a year earlier. The unemployment rate was 3.4 percent, compared with 3.5 percent a year earlier.
Source: Bureau of Labor Statistics, Local Area Unemployment Statistics and Current Employment Statistics. September 2026 figures are preliminary. October 2025 unemployment data were not collected during the 2025 federal funding lapse. October 2026 metro figures are due Dec. 2.See the numbers
People keep coming, too. In the year that ended July 1, 2025, the metro added 17,395 residents, according to the Census Bureau’s latest estimates. More Americans moved into the region than left it for the third year in a row, and the margin grew each year: 2,861, then 4,471, then 5,170. Immigration, which drove the jump the year before, fell by more than half, to 6,083.
The gains are uneven. Johnson County added 6,074 people, the most of the five core counties, and swung from losing domestic movers to gaining them. Clay and Platte Counties drew steadily from elsewhere in the country. Wyandotte County lost 976 more residents to other parts of the country than it gained, and grew only because of immigration and births.
Where the metro’s growth came from, by year
Population change in the 14-county Kansas City metro, years ending July 1
Moved from elsewhere in the U.S., netImmigration, netBirths minus deaths
Who moved in, county by county
Year ending July 1, 2025. Each dot is 20 people, net.
U.S. moversU.S. movers leavingImmigrants
Takeaway. In the year that ended July 1, 2025, the metro added 17,395 residents. More Americans moved into the region than left it for the third year in a row.
Source: U.S. Census Bureau, Vintage 2025 population estimates, components of change. Dots show net totals; their paths are illustrative and do not show where people came from.See the numbers
What’s next
What should we watch in the Kansas City housing market this winter?
October is a first draft. One earlier count, 24,817, was later revised to 26,378, so the 19.8 percent drop in contracts could shrink.1
What to watch this winter
The October numbers are a first draft. Early counts tend to be revised upward: in KCRAR reports from October 2024 to September 2025, one first-reported count of 24,817 was later revised to 26,378, 6.3 percent higher. October’s 19.8 percent drop in contracts could shrink.
Longer-term projects keep shaping where people want to live. The streetcar’s Riverfront extension opened May 18. On Oct. 8, the City Council took up measures tied to a proposed Royals stadium at Crown Center. Panasonic’s battery plant in De Soto, in western Johnson County, is still hiring.
How this was reported
Market figures come from the Kansas City Regional Association of Realtors’ Local Market Updates for October 2026 (all residential, current as of Nov. 7), and from Saving KC’s extracts of the Heartland MLS Matrix system: a Nov. 9 rollup of October closings by ZIP code and a Nov. 2 listing extract with sale terms, which supplies cash shares. The two extracts are different vintages and are never mixed in one figure. County figures compare October 2026 as first reported with October 2025 as revised.
Rates and payments use Freddie Mac’s weekly 30-year average. Payments are principal and interest only, on 75 percent of the median price. The six-week comparison is the change between weekly readings six weeks apart; the last six-week rise of at least 0.74 points ended Oct. 27, 2022.
Jobs come from the Bureau of Labor Statistics for the Kansas City, MO-KS metropolitan area. Population comes from the Census Bureau’s Vintage 2025 estimates (counties and the 14-county metro), years ending July 1.
Rental math covers the 71 ZIP codes with at least 10 October sales and uses unrounded ratios. Of 111 ZIP codes with any October sales, 40 had fewer than 10 and are left out of that calculation rather than estimated.
October expired and withdrawn counts of 151 expired and 81 withdrawn (232 total) are a narrower Matrix slice, not a full fail rate. A still narrower extract of 55 listings in 20 ZIP codes with at least 20 October sales and a median close price from $200,000 to $400,000 is shown only as county and ZIP aggregates: counts, and median last list price and median days on market where a group has at least five listings. No MLS numbers, addresses or single-listing details are published. What this can’t show: who the cash buyers are, sales that never reach the MLS, or why any individual listing failed to sell. Figures from different sources cover slightly different areas: the KCRAR metro row covers 19 counties, the ZIP data covers five, and the Census metro covers 14.
What this means for you
This page is a market report, not a price quote and not a cash offer. If you are deciding what to do with a house in the Kansas City metro, a local team can walk through your options in plain English. No pressure and no obligation.
Copy-ready summary
Sources
Kansas City Regional Association of Realtors, Local Market Updates, October 2026, current as of Nov. 7, 2026 (pending sales, closed sales, median prices, inventory, months of supply, sale-to-list ratios, days to contract). September 2026 county updates supply the gross and net fail rates.
Freddie Mac Primary Mortgage Market Survey, 30-year fixed average, including 6.22 percent in the week of Nov. 6, 2025; the 7.40 percent peak in the weeks of Oct. 8 and Oct. 15, 2026; and 7.18 percent in the week of Nov. 5, 2026. freddiemac.com/pmms
Heartland MLS (Matrix) extracts by Saving KC: a Nov. 9, 2026 ZIP rollup of October closings, a Nov. 2, 2026 listing extract with sale terms (cash share), and an Oct. 1-31, 2026 expired/withdrawn extract used only as aggregates. Area totals only; no listing-level records are published.
Bureau of Labor Statistics, Local Area Unemployment Statistics and Current Employment Statistics for the Kansas City, MO-KS metropolitan area. September 2026 figures are preliminary. bls.gov/lau and bls.gov/ces
National Association of Realtors, September 2026 existing-home months of supply, used as the national comparison of 4.8 months. nar.realtor/research-and-statistics
Ready to talk through your Kansas City house?A local team. A written cash offer.
Ernest Dodson is an Acquisitions Analyst at Saving KC Homebuyers, a Kansas City metro real estate investing company with 11+ years of local experience. His focus is tax-delinquent homes and inherited property. The team has helped 100+ homeowners ready to sell find a way forward. You'll also find him on YouTube at @SavingKC, where he explains property taxes, tax sales, and the Kansas City housing market in plain English. Have questions? Reach out and let's talk.
Disclosure. Ernest Dodson is a Missouri-licensed real estate salesperson with Platinum Realty LLC (MO License No. 2023026433). Saving KC Homebuyers buys houses as an investor. One or more principals of Saving KC Homebuyers hold a real estate license in Missouri with Platinum Realty LLC. Educational information only; not legal, tax or investment advice. Figures are from the sources named in this report and may be revised.
Home walkthrough
Pick a time that works.
Schedule a home walkthrough, or ask for a phone call first. Weekday times are 8 to 5 CT. Saturday mornings are 9 to noon. No Sunday times. Saturday visits are appointments. The office is closed Saturday and Sunday.
SunMonTueWedThuFriSat
Open timesTimes in CT
Pick a day to see open times.
No obligation
Nothing to fix or clean
Confirmed by text
Questions this report answers
How many contracts were signed in October?
Buyers signed 2,506 contracts in October, 19.8 percent fewer than a year earlier, when they signed 3,123. That is 617 fewer contracts. Closings lag contracts by a month or more, so the full effect has not reached the sales totals yet. Closed sales still fell 10.6 percent in October, to 2,953.
Did home prices fall?
The median sale price held at $330,000. With 2.9 months of supply, the region has far fewer homes for sale than the nation, at 4.8 months. Medians fell in Johnson, Platte and Clay Counties. The higher rate erased those discounts everywhere.
How high did mortgage rates go?
The 30-year mortgage rate peaked at 7.40 percent in the weeks of Oct. 8 and Oct. 15, its highest since November 2023. From late August to early October, the average rose from 6.66 percent to 7.40 percent, the largest six-week climb since the fall of 2022. Rates have eased since, to 7.18 percent on Nov. 5.
Where did monthly payments rise the most?
The monthly payment on a typical home rose most in Jackson and Wyandotte Counties, by 15 to 16 percent, because prices and rates went up together there. The payment on the typical Jackson County home is up $207 a month, or 16 percent. In Wyandotte County it is up 15 percent.
Are unsold homes piling up?
Active listings rose just 1.5 percent from a year earlier, to 9,139. At October’s pace of sales, that is 2.9 months of supply, the same as last year. Across Heartland MLS, homes sold for 96.4 percent of their original asking price, down from 96.9. Jackson County is the exception: the only core county where homes took longer to sell, 46 days instead of 38, and the only one with more than three months of supply.
How common are cash buyers?
Across all five core counties, 19.9 percent of October sales were cash. Below $150,000, it was 56.2 percent. Every one of the 10 homes that sold for under $50,000 went to a cash buyer. The share falls to 12.7 percent between $350,000 and $400,000, then climbs again above $400,000.
Can a financed rental still cover the mortgage?
At 7.18 percent with 25 percent down, a rental needs a capitalization rate of about 7.62 percent to cover its mortgage with a 25 percent cushion. The typical ZIP code with enough sales to measure produced 3.84 percent. Five of 71 cleared the bar. All five are in Jackson County, with median prices under $170,000.
Why are cash buyers paying cash, and what do they earn?
In most ZIP codes, negative leverage makes cash the better choice, because the cap rate is below the 7.62 percent a loan needs. In the cheapest ZIP codes the math would favor a loan, but those houses often cannot get conventional financing because of their condition. Cash also closes faster. That is why 56.2 percent of sales below $150,000 were cash, and every sale below $50,000 was cash. For an all-cash rental, cash-on-cash before income taxes equals the cap rate. The five ZIP codes that clear 7.62 percent, all in Jackson County, yield 12.72, 12.36, 11.05, 8.03 and 8.00 percent.
Is the region still growing?
The Kansas City metro had 1,175,300 payroll jobs in September, 6,000 more than a year earlier. The unemployment rate was 3.4 percent. In the year that ended July 1, 2025, the metro added 17,395 residents. More Americans moved into the region than left it for the third year in a row.
How many Kansas City listings failed to sell?
In September, 28.9 percent of Jackson County listings and 33.5 percent of Wyandotte County listings that left the market did so without a sale. In October, 151 listings expired and 81 were withdrawn across the five core counties, 232 in all. Those October counts are a narrower Matrix slice, not a full fail rate.
Where are homes selling fastest and slowest, and why?
Among ZIP codes with 10 or more October sales, 66207 in Johnson County was fastest at 2 days to contract, and 64128 in Jackson County was slowest at 58 days. The typical Johnson County ZIP code was about eight days, and the typical Jackson County ZIP code about 25. The five fastest have a middle price of $445,000 and a middle cash share of 20.0 percent, against $230,000 and 30.0 percent for the five slowest. Three of the five fastest are in Johnson County and four of the five slowest are in Jackson County. Those are correlations, not causes. The 30-year rate peaked at 7.40 percent the same month, and the Jackson County payment is up $207 a month, or 16 percent. In the expired and withdrawn slice, 64133 and 64138 sat a median 121.5 and 123 days, a different clock from days to contract on homes that sold.
Questions about the data, or about selling a house?
This is a market report, not a price quote and not a cash offer. If you want a plain-English look at your options, talk with a local Kansas City team. No pressure and no obligation.